The retirement accounts won't wait for you to feel ready
You're standing at a custodian's phone queue, grief-fogged and unprepared, while a representative rattles off acronyms you've never heard — RMD, RBD, SECURE 2.0, deemed disposition. They need you to make decisions right now about rollovers, distribution elections, and tax withholding. You didn't ask for any of this.
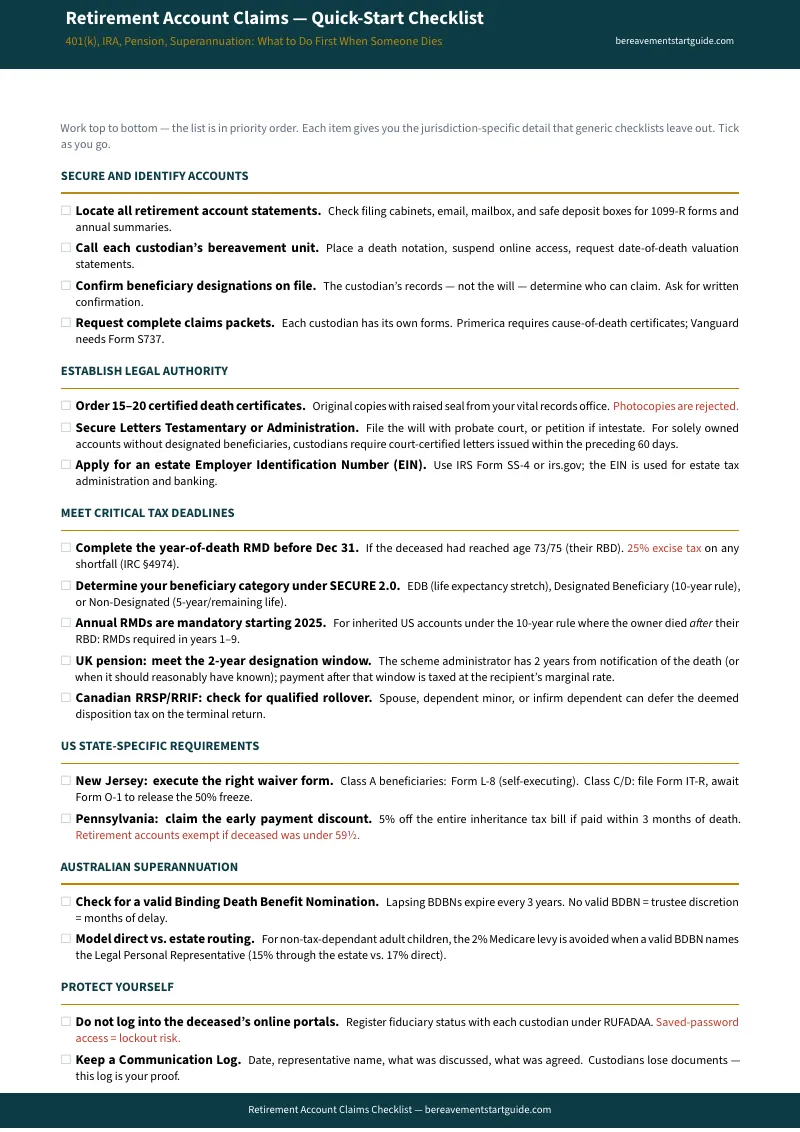
Meanwhile, the deadlines are already running. Miss the year-of-death Required Minimum Distribution and the IRS charges a 25% excise tax on the shortfall. Fail to designate a UK pension within two years of the scheme being notified and tax-free status disappears entirely. Let a Canadian RRSP sit unaddressed and the full value gets reported as taxable income on the terminal return — often at the highest marginal bracket.
Free advice online covers fragments of this. Government portals explain the rules in language designed for financial professionals. What nobody gives you is the complete sequence — the exact steps, in the right order, for the right jurisdiction, with the forms pre-identified and the scripts ready to use.
The Retirement Claim Roadmap — built for grief, not for accountants
This is a step-by-step claims toolkit covering inherited 401(k)s, IRAs, pensions, and superannuation across the United States, United Kingdom, Canada, and Australia. It translates dense tax regulations into plain-language workflows and gives you the tools to execute them — even when your brain is running on two hours of sleep and your third cup of coffee.
Every chapter is built around a single principle: you should never have to figure out what to do next. The guide tells you what to open, who to call, what to say, what to file, and when — with custodian-specific form numbers, pre-written email scripts, and worked tax calculation examples you can follow with a calculator.
What's inside
- First 72 hours protocol — secure accounts, prevent unauthorized access under RUFADAA, and order the right death certificates before custodians reject your paperwork
- Jurisdiction-specific claim chapters — dedicated chapters for US (SECURE Act 2.0 rules, 10-year depletion, spousal rollover elections), UK (pre/post-75 tax treatment, LSDBA limits, 2027 IHT reforms), Canada (deemed disposition, qualified beneficiary rollovers, cross-border RRSP traps), and Australia (super death benefits, tax-dependant vs. non-dependant treatment, withdrawal and re-contribution strategies)
- Four custodian email scripts — pre-written correspondence for death notification, follow-up, year-of-death RMD requests, and distribution elections. Customize the bracketed fields and send.
- Year-of-death RMD calculator walkthrough — step-by-step worked examples using the IRS Single Life Table so you can verify the calculation yourself instead of trusting a phone representative's mental math
- State inheritance tax waiver procedures — state-specific forms and processes for jurisdictions like New Jersey (Form L-8 self-executing affidavit or the IT-R/O-1 Tax Waiver process) and Pennsylvania (5% early payment discount)
- Beneficiary category decision tree — determine whether you're an Eligible Designated Beneficiary, a Designated Beneficiary under the 10-year rule, or a Non-Designated Beneficiary, and what each classification means for your distribution timeline
- Eight printable planning tools — retirement account tracker, communication log, document submission log, RMD distribution planner, beneficiary decision tree, family meeting agenda, and fiduciary decision log
Who this is for
- Surviving spouses weighing a spousal rollover against an inherited IRA election — the guide walks through both paths with tax implications
- Adult children facing the 10-year depletion rule and trying to figure out whether annual distributions are required (they are, if the owner died after their RBD)
- Estate executors and administrators managing multiple retirement accounts across different custodians, each with their own forms and timelines
- Families with accounts in multiple countries navigating overlapping tax obligations, withholding treaties, and different regulatory frameworks
- Anyone who just learned that the will doesn't control who gets the retirement accounts — the beneficiary designation does
Why not piece it together from Google?
You could. Families typically spend 40+ hours gathering fragmented information from government portals, custodian help pages, and forum posts — and they still miss critical steps. Research from Zurich UK found that structured bereavement support saves families an average of 148 administrative hours and over £2,300 in direct estate costs.
The real risk isn't the time — it's the mistakes you don't know you're making. Missing a SECURE Act 2.0 annual RMD triggers an automatic 25% penalty. Failing to designate UK pension funds within the two-year window forfeits tax-free status permanently. Naming the estate as a Canadian RRSP beneficiary instead of a qualified individual eliminates the rollover option and triggers immediate taxation at the highest bracket.
This toolkit consolidates the current rules, the jurisdiction-specific procedures, and the custodian-specific forms into a single resource — so you're not discovering a deadline after you've already missed it.
Full refund, no time limit
If the toolkit doesn't help, email hello@bereavementstartguide.com for a full refund. No time limit, no conditions.
The free checklist gives you the critical steps. The full toolkit — — gives you the system to execute them: scripts, worksheets, worked examples, and jurisdiction-specific guidance that turns a months-long administrative burden into a clear sequence you can follow one step at a time.